The Future of Digital Assets: From Investment to Everyday Spending
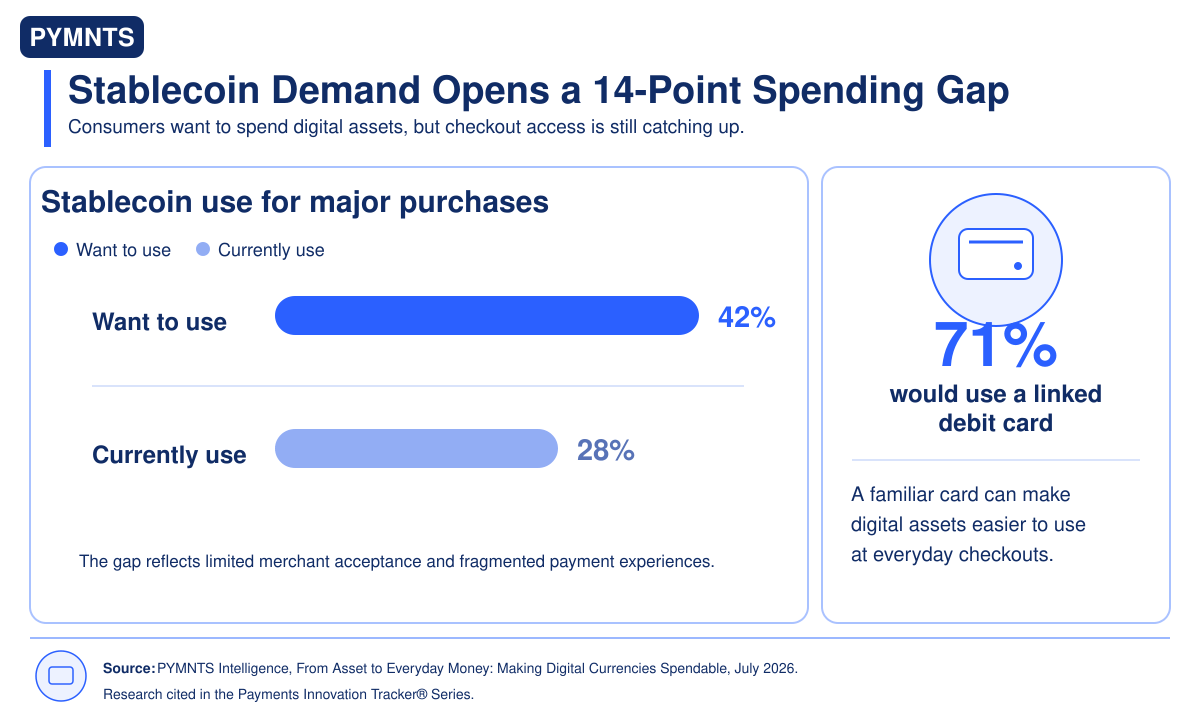
The world of digital assets is evolving rapidly, and consumers are eager to see cryptocurrencies and stablecoins become a part of their daily financial routines. A recent study by PYMNTS Intelligence and Paymentology reveals a fascinating trend: while digital assets are gaining traction, there's a significant gap between ownership and actual usage at the checkout. This 14-percentage-point gap highlights a crucial challenge—how do we bridge the divide between digital asset ownership and everyday spending?
From Wallets to Wallets with Debit Cards
One of the most intriguing solutions is the integration of stablecoins with traditional banking systems. Imagine a world where your stablecoins are seamlessly connected to your debit card. This is not just a pipe dream; 71% of stablecoin holders are ready to embrace this idea. By linking stablecoins to debit cards, users can spend their digital assets just like they would with any other currency, making the transition from asset to everyday money incredibly smooth.
Personally, I find this concept revolutionary. It addresses a fundamental issue with digital assets—their perceived complexity. By utilizing familiar tools like debit cards, we can make digital assets more accessible and less intimidating. This approach could be the key to unlocking the full potential of cryptocurrencies and stablecoins in the mainstream economy.
Building Trust with Familiarity
Trust is a cornerstone of any financial system, and digital assets are no exception. Interestingly, the study found that 77% of consumers would prefer to open a crypto or stablecoin wallet through their existing banking or FinTech app. This preference highlights a critical aspect of consumer behavior—they seek familiarity and trust.
In my opinion, this is a powerful insight for banks and FinTechs. By integrating digital assets into existing financial platforms, these institutions can leverage their established trust and user base. This not only simplifies the user experience but also makes digital assets more approachable for the average consumer. It's a win-win situation, as it expands the market for digital assets while providing banks and FinTechs with a new avenue for growth.
Beyond Consumer Spending
The potential of digital assets extends far beyond consumer spending. The report reveals a staggering 15-fold increase in monthly crypto card spending from early 2023 to late 2025, reaching an annualized rate of approximately $18 billion. This growth is not limited to individual purchases; it's a testament to the broader acceptance and utility of digital assets.
What many people don't realize is that stablecoins are also making significant inroads in the business world, particularly in cross-border payments. Their ability to provide faster settlement, lower costs, and access to stable currency values is solving real-world problems for businesses. This trend suggests that digital assets are not just a fad but a viable alternative to traditional financial systems.
Overcoming Barriers
However, challenges remain. The study identifies limited merchant acceptance, transaction costs, volatility, and fraud concerns as significant barriers. These issues are not unique to digital assets but are common growing pains for any disruptive technology.
From my perspective, addressing these challenges requires a multi-faceted approach. Firstly, increasing merchant acceptance will be crucial, as it will provide more opportunities for consumers to spend their digital assets. Secondly, reducing transaction costs and mitigating volatility will make digital assets more attractive for everyday use. Lastly, enhancing security measures and educating users about fraud prevention will build trust and confidence in the system.
The Path Forward
The report offers a measured yet optimistic outlook, emphasizing the potential of linked cards, real-time conversion, and modern issuer processing. By connecting digital assets to familiar banking systems, we can make them more spendable without burdening consumers and merchants with a steep learning curve.
In conclusion, the future of digital assets is not just about their value as investments but also their role in everyday transactions. By bridging the gap between ownership and spending, we can unlock the true potential of cryptocurrencies and stablecoins. As an expert in the field, I believe this is a pivotal moment for the digital asset ecosystem, and the innovations we see today will shape the financial landscape of tomorrow.